Your refuse truck clipped a parked car on a Tuesday morning route. Three weeks later, the claim is still open, the adjuster is asking for photos nobody took, and your risk pool wants a repair cost breakdown your shop kept on paper. That is the reality of fleet insurance claims in most government fleets: the accident takes seconds, but the documentation chase drags on for 4 to 6 weeks, tying up your vehicle, your staff hours and your loss run record. Municipal and county fleets that self-insure through pools like NLC Mutual or follow PRIMA risk standards live and die by their claim file - photos, police report, work order costs, rental invoices and a subrogation letter, all in one package. The fleets closing claims in days instead of weeks are not luckier; they are the ones whose maintenance and inspection records already live in one system, so the claim pack practically builds itself. If you want to see what a 3-minute claim package looks like on your own units, book a 30-minute walkthrough with the HVI team and bring a real claim scenario.
What does a defensible fleet insurance claim file actually contain?
Five documents decide whether your claim closes in 3 days or 6 weeks - and whether your pool premium goes up next renewal. Miss one and the adjuster owns the timeline, not you.
What a 6-week claim really costs a municipal fleet
Every week a claim sits open, you pay in four directions at once: the unit is down, the rental meter runs, staff chase paperwork, and your loss run report ages badly in front of the pool board.
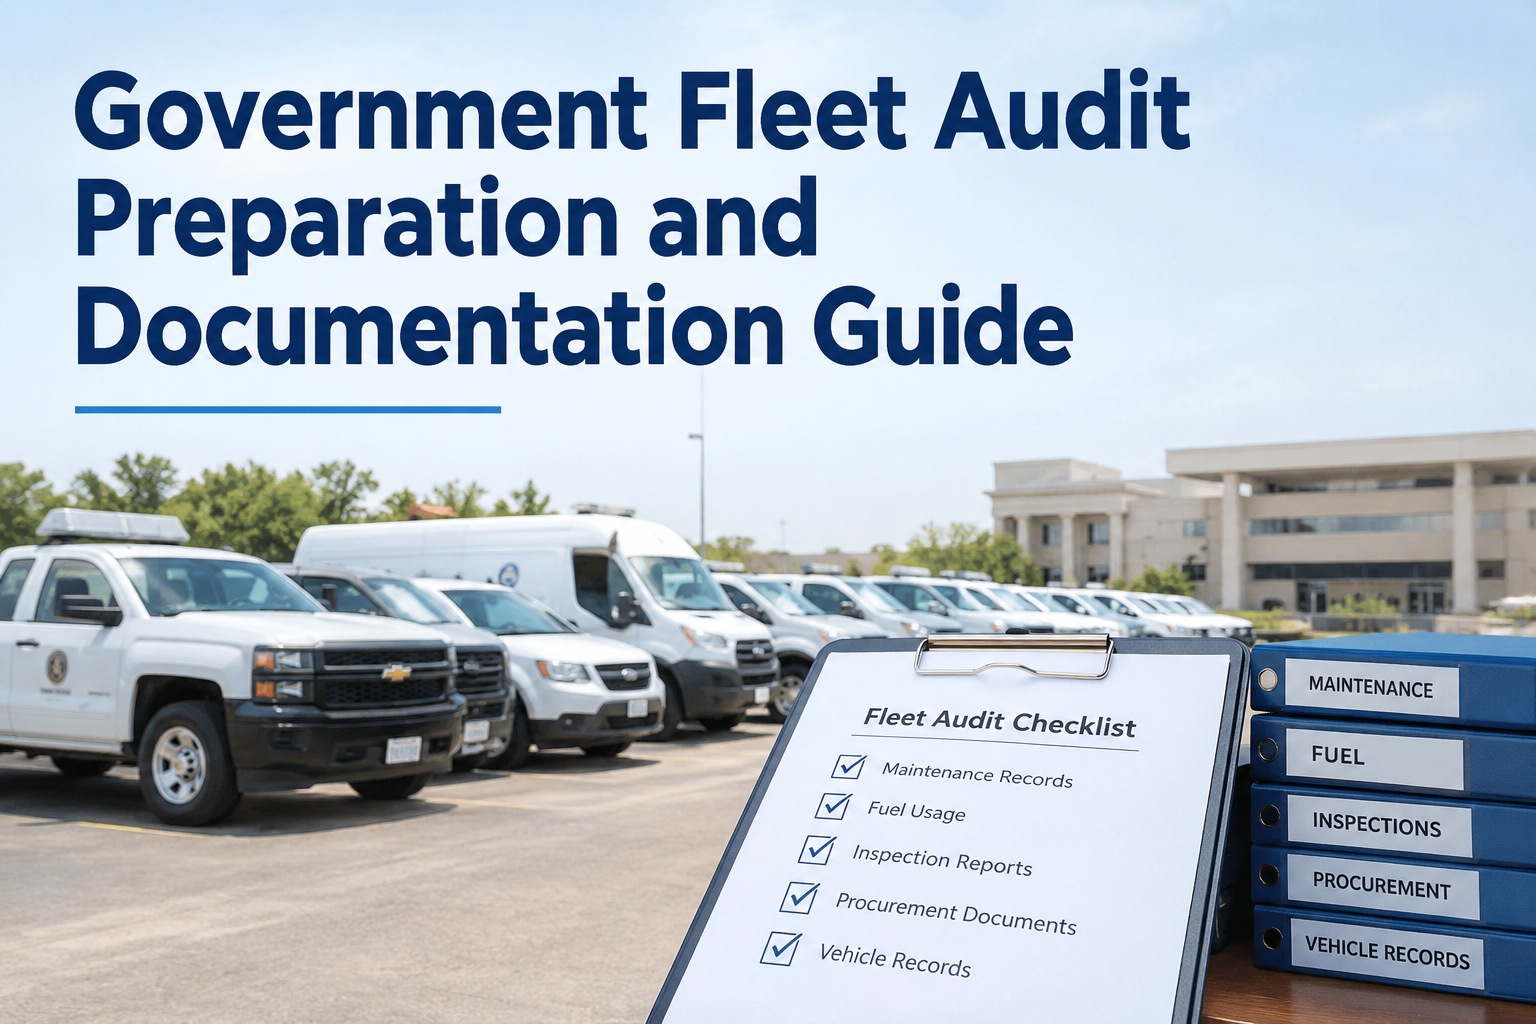
The 5 documents every government fleet insurance claim needs
Adjusters and risk pools - whether you are with NLC Mutual, a county risk retention group or a commercial carrier - ask for the same five things. Here is what each one proves and where it usually goes wrong.
Scene and damage photos
Timestamped photos of the vehicle, the damage, the scene and any third-party property. The failure mode: photos live on a driver's personal phone, get texted to a supervisor, and lose their metadata. Without a timestamp, the other side's counsel can question when and where they were taken.
Police or incident report
The official report number, responding agency and narrative. The failure mode: the report sits in a shared drive folder named after the driver, and nobody links it to the unit number, so the adjuster gets it two weeks late.
Repair work order with full cost breakdown
Labour hours, parts, sublet work and totals tied to the specific unit. The failure mode: the repair was logged on a paper work order or in a spreadsheet, parts were pulled without being costed to the job, and the number you send the adjuster does not match the number finance has.
Rental and downtime cost log
Daily rental invoices plus the dates the unit was out of service. The failure mode: downtime is estimated from memory, so you either under-claim and eat the cost, or over-claim and lose credibility with the pool.
Subrogation demand letter
When the third party is at fault, your demand letter needs every cost above attached and itemised. The failure mode: the letter goes out with a round-number estimate, the other carrier lowballs, and you settle for 60 cents on the dollar because you cannot prove the rest.
Paper files vs a digital claim package: the same accident, two outcomes
Take a real scenario: a 40-vehicle county public works fleet, a plow truck rear-ended at a stoplight, third party at fault. Here is how the next six weeks play out depending on where your records live.
Paper binders and group chats
- Day 1-5: supervisor collects photos from two phones, one set is blurry, timestamps lost
- Day 8: police report arrives, filed under driver name not unit number
- Day 15: shop rebuilds the repair cost from memory and parts invoices - $400 discrepancy with finance
- Day 30: adjuster requests maintenance history to check for pre-existing damage; you need a week to pull it
- Day 42: subrogation settles at a discount because downtime was never documented day by day
HVI digital claim package
- Day 1: driver photographs damage in the HVI app - timestamped, geotagged, attached to the unit
- Day 1: incident report number logged against the asset record
- Day 2: repair work order opened from the same record; every part and labour hour costed automatically
- Day 3: downtime and rental log exported with the unit's full inspection and PM history
- Day 3: one zip file - photos, report, work order, costs, rental log - goes to the adjuster and the subrogation letter goes out itemised
The difference is not effort - it is where the records were born. When inspections, defects and work orders already live in one CMMS, the claim file is a by-product, not a project. You can start building that record trail free before your next incident, not after it.
The math your risk pool board will ask about
Government fleet risk management is a numbers game at budget time. Run this example with your own figures - it is the same calculation a pool actuary does on your loss run.
That is before the premium effect. Pools and carriers price on your loss run: open claims with reserves sitting against them, and settlements discounted for weak documentation, both push your experience mod the wrong way. Fleets that walk through their claims process in a demo usually find the software pays for itself on the first subrogation they recover in full.
See a claim package built live on your own fleet data
Bring a real incident from the last year. In 30 minutes we will show you exactly what the adjuster would have received - and how fast.
How HVI turns fleet insurance claims into a 3-minute export
HVI is not claims software - it is the inspection and maintenance system where the evidence is created in the first place. Four capabilities do the heavy lifting when a claim lands.
Photo-backed inspections and incidents
Drivers and supervisors capture damage photos in the app at the scene - timestamped, attached to the unit, impossible to lose in a text thread. The same photo trail that proves a DVIR proves your claim.
Work orders with true repair cost
Every repair is a digital work order: labour hours, parts pulled from inventory, sublet invoices - all costed to the unit automatically. When the adjuster asks for the breakdown, you export it, you do not rebuild it.
Downtime and status history per asset
Unit status changes are logged with dates, so out-of-service windows and rental periods are documented day by day - the difference between a defensible downtime claim and a negotiated guess.
One-click audit and loss reports
Full unit history - inspections, PM compliance, defects, repairs, costs - exports as a single package. Adjusters, pool auditors and council members all get the same clean, timestamped record.
Because HVI runs on any phone or tablet, the evidence capture happens at the roadside, not back at the office. If your fleet still builds claim files from binders and inboxes, see the export for yourself in a short demo - it is the fastest way to judge the gap.
Meeting NLC Mutual and PRIMA documentation standards without extra admin
Risk pools and public entity insurers do not ask for anything exotic - they ask for consistent, provable records. The gap is that most fleets produce those records on paper, where they cannot be searched, linked or exported.
| What the pool or carrier asks for | Paper-based fleet reality | With HVI |
|---|---|---|
| Pre-incident vehicle condition | Daily check sheets in a binder, if the driver filed them | Timestamped DVIR history with photos per unit |
| PM compliance at time of loss | Spreadsheet updated weekly, gaps hard to explain | PM schedule with due/overdue alerts and completion log |
| Itemised repair cost | Handwritten work order plus separate parts invoices | Work order with labour, parts and sublet costed automatically |
| Downtime and rental period | Estimated from memory and email threads | Asset status log with exact out-of-service dates |
| Loss run support at renewal | Two weeks of staff time assembling files | Per-unit and fleet-wide cost and incident reports on demand |
Fleets that move inspections and work orders into HVI typically find renewal season gets quieter: the loss run conversation shifts from defending gaps to discussing trends.
Fleet insurance claims: what to remember before the next incident
Speed is a documentation problem, not an adjuster problem
Claims close in 3 days when the five documents arrive together. They drag to 6 weeks when you assemble them after the fact. The adjuster's timeline is a mirror of your filing system.
Subrogation is where the money is
When the third party is at fault, an itemised demand letter backed by timestamped photos and costed work orders recovers in full. A round-number estimate settles at a discount - every time.
Your loss run is written all year, not at renewal
Every open claim with a reserve against it, and every discounted settlement, lands on your loss run and prices your next premium. Clean fleet insurance claims documentation is premium defence.
The fix is upstream
You cannot document a claim well at the adjuster's desk if the evidence was never captured at the roadside and in the shop. Move inspections, defects and work orders into one CMMS and the claim pack builds itself. Book a demo and test it against your last real claim.
The claim that taught me was a backed-into loader - clear third-party fault, and we still settled light because nobody could prove eleven days of downtime. Now I check one number every month: days from incident to claim package sent. If it is over three, something in our process broke. Since we put inspections and work orders in one system, that number is basically the same afternoon.
Fleet insurance claims FAQs for government fleets
What documents do I need for a fleet vehicle insurance claim?
How long does a municipal fleet insurance claim take to close?
How does poor documentation affect our risk pool premium?
What is subrogation in a fleet accident claim?
Can maintenance software really help with insurance claims?
Your next claim file is being written right now
Every inspection, defect and work order your fleet logs this month is the evidence a future adjuster will ask for. Make sure it is timestamped, photo-backed and exportable.
Free to start - Works on any phone - No card needed