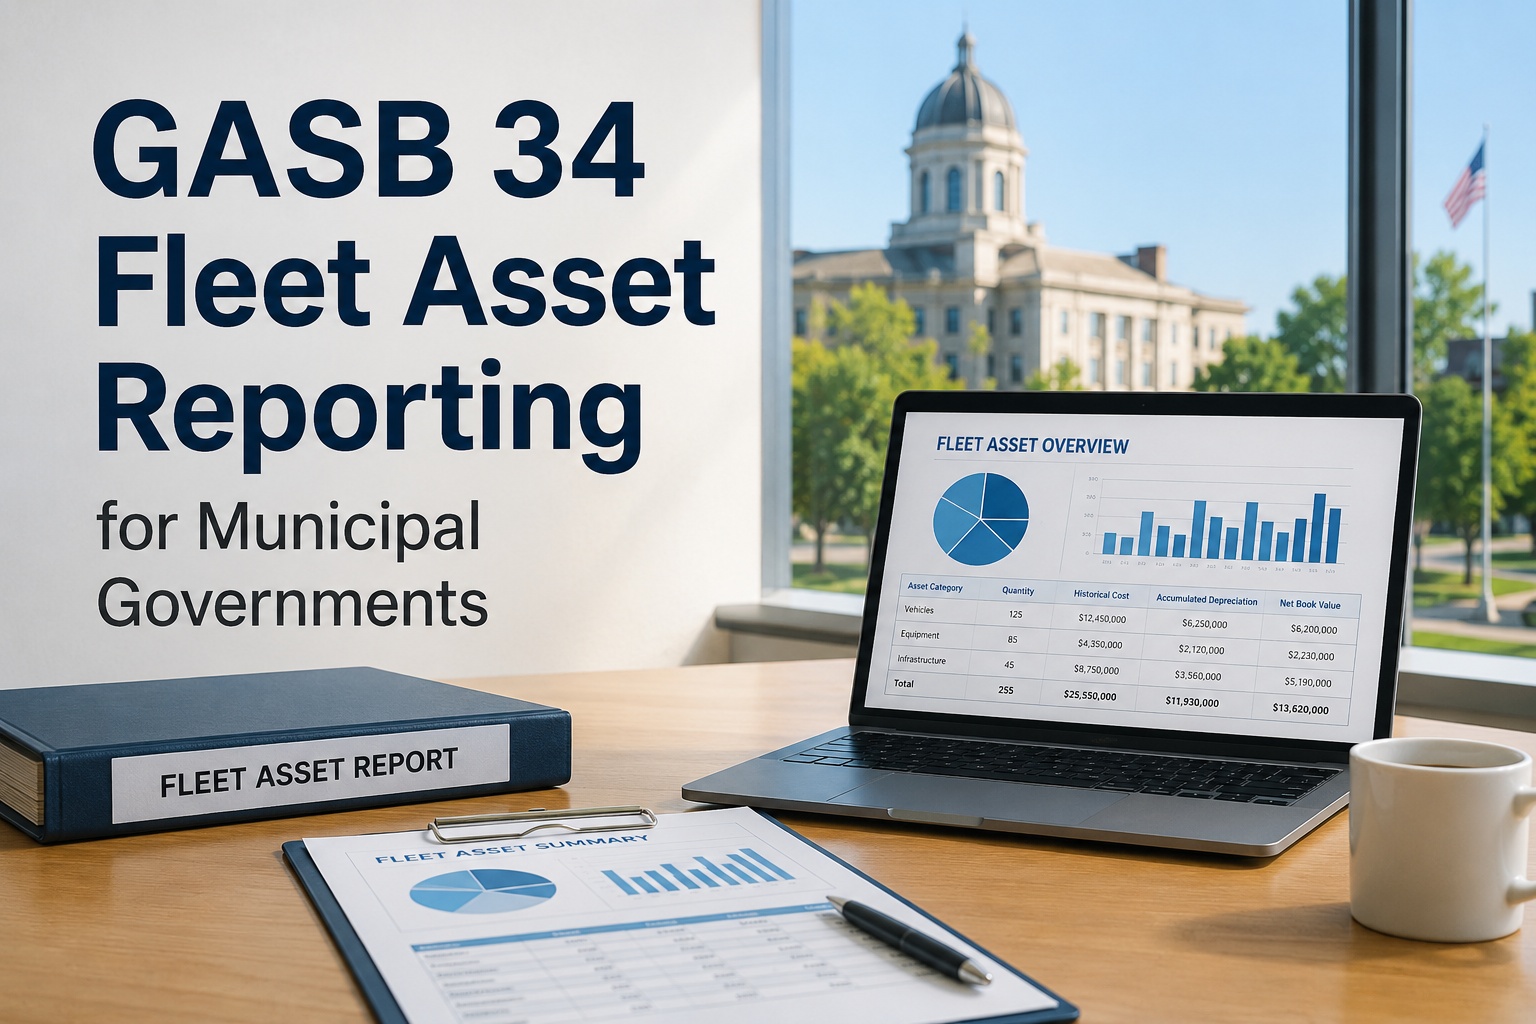
It's June. Your finance director emails at 4:47 PM on a Friday: the auditors want the full capital asset schedule for the fleet by Wednesday — acquisition cost, in-service date, useful life, accumulated depreciation, the lot. You open the spreadsheet. Three of the columns are blank, two trucks were disposed of in 2022 but never removed, and nobody can remember whether the new loader was capitalized or expensed. This is where GASB 34 fleet reporting stops being an accounting footnote and becomes your problem. GASB Statement 34 requires every state and local government to capitalize and depreciate moveable assets — and for most municipalities, the vehicle and equipment fleet is the single largest line on that schedule. HVI's fleet asset ledger keeps every unit's acquisition data, cost history, and depreciation schedule audit-ready year-round, so the June email is a ten-minute export instead of a three-week archaeology project. If you'd rather see it working on your own asset list first, you can book a 30-minute walkthrough with our team and bring your messiest spreadsheet.
Is your fleet the biggest number on your GASB 34 schedule — and the least documented?
For most public works and municipal fleets, vehicles and equipment make up 40–70% of the government's total moveable capital assets. Yet that data usually lives in a spreadsheet last touched during the previous audit. HVI turns your fleet into a clean, continuously updated fixed-asset register — acquisition to disposal.
- Depreciation recalculated by hand every June
- Disposed units still on the books for years
- Audit prep measured in weeks, not minutes
- Straight-line schedules auto-generated per unit
- Disposals and transfers timestamped and logged
- One-click export your auditors actually accept
The real price of a spreadsheet-based fleet register
GASB 34 asset depreciation isn't optional, and it isn't cheap to get wrong. These are the four numbers municipal fleet managers feel most directly.
GASB 34, 87 and 96: what each statement actually demands from your fleet records
Three statements drive almost all of your fleet's financial reporting obligations. Here's what each one expects you to know about every unit you own, lease, or subscribe to.
Capital assets & depreciation
Every vehicle or piece of equipment above your capitalization threshold (commonly $5,000) goes on the books at acquisition cost, gets assigned an asset class and useful life, and is depreciated — typically straight-line — over that life. You must track accumulated depreciation, additions, disposals, and transfers, and report net book value annually. A dump truck on a 10-year life and a police sedan on a 5-year life depreciate differently; your records have to reflect that, unit by unit.
Leased fleet assets
Most vehicle and equipment leases are no longer "operating leases" that live off the balance sheet. Under GASB 87, a lease creates a right-to-use asset and a corresponding lease liability, both reported on your government-wide statements. That means every leased grader, sweeper, or pool sedan needs its lease term, payment schedule, and discount rate documented — and remeasured when terms change.
Subscription-based IT (SBITAs)
The fleet software subscriptions you rely on — telematics, GPS, CMMS platforms — are themselves capitalizable as subscription assets under GASB 96 when the contract runs longer than 12 months. Finance needs the contract value, term, and implementation costs. When your fleet data already lives in a documented CMMS, handing finance those numbers takes one email instead of a procurement dig.
What a GASB-ready fleet asset record actually contains
Auditors don't ask for stories — they ask for fields. This is the mapping between what GASB 34 fleet reporting requires and where HVI captures it during normal daily operations.
| GASB 34 schedule field | Where it usually lives | Where HVI captures it |
|---|---|---|
| Asset description, class & serial/VIN | Spreadsheet + paper title file | Asset profile with photos, VIN, class and custom fields |
| Acquisition date & cost | Purchase order in finance system | Acquisition record on the unit, synced to integrations |
| Useful life & depreciation method | Finance policy memo | Per-unit schedule: straight-line, class-based useful life |
| Accumulated depreciation | Recalculated annually by hand | Auto-computed monthly, exportable any time |
| Additions & improvements | Work orders, if they're kept | Every work order costed against the unit automatically |
| Disposals, transfers & gain/loss | Email chains and memory | Disposal workflow with date, proceeds and timestamp |
The difference isn't the fields — it's when they're captured. HVI records them as work happens, not in a June panic. You can see the full asset ledger in a live demo using your own unit list.
One fleet, one schedule: a 120-unit municipality, start to finish
Here's what the math looks like for a mid-size public works fleet — and why the capitalization threshold decision matters more than most managers realize.
Set the threshold and asset classes
The city capitalizes anything over $5,000. Fleet units fall into classes: light vehicles (5-year life), heavy trucks (10-year), off-road plant (12-year), small equipment (7-year). Everything under threshold — the $3,200 pressure washer, the $1,800 floor jack — is expensed and never touches the schedule.
Capitalize at acquisition cost
A new tandem-axle dump truck arrives at $218,000 including upfit. HVI logs the in-service date, cost, class and VIN the day it's inspected into the fleet — the same record the shop will use for PM scheduling and work orders for the next decade.
Depreciate straight-line over useful life
That truck depreciates at $21,800 per year over its 10-year life. Multiply across 120 units and the fleet's annual depreciation expense lands around $640,000 — a number finance needs exactly, not approximately, for the government-wide statements.
Record disposals the day they happen
A 14-year-old sweeper goes to auction and brings $11,000. Its net book value was $8,400, so the schedule shows a $2,600 gain on disposal. Logged in HVI on disposal day, it never becomes the ghost asset auditors find three years later.
Run this across your own fleet and the pattern is clear: the depreciation math is easy — it's the data capture that breaks. That's the part HVI automates. Create a free account and load your first units to see the schedule build itself.
Your auditors want a schedule. Give them an export.
See HVI's fleet asset ledger and GASB-ready depreciation reporting running on units like yours — dump trucks, sweepers, loaders and all.
Five GASB 34 fleet reporting mistakes auditors find first
Municipal auditors see the same fleet findings year after year. Every one of these is a data problem, not an accounting problem — which means every one is fixable at the source.
Ghost assets
Units sold, scrapped or traded years ago still sitting on the schedule, still depreciating. If your register says 142 units and your yard says 131, you have a finding. HVI's disposal workflow closes the loop the day a unit leaves.
Missing acquisition costs
Older units with no recorded cost get valued at estimates — and estimates get challenged. Photo-backed asset profiles with original PO data attached end that conversation before it starts.
Wrong useful lives
A patrol sedan depreciated over 12 years and a loader over 5 both distort the statements. Class-based defaults in HVI keep every unit on a defensible life that matches policy.
Unrecorded improvements
A $28,000 engine repower extends useful life and belongs on the schedule as an addition. When work orders carry costs against the unit automatically, nothing material slips through.
Leases left off the books
Under GASB 87, that "simple operating lease" on three pool sedans is a right-to-use asset with a liability attached. Fleets that track lease terms centrally hand finance the remeasurement data without a scavenger hunt.
The June reconstruction
Rebuilding twelve months of acquisitions, transfers and disposals from emails is the most expensive way to comply — typically 2–3 weeks of staff time every single year. Continuous capture makes the annual close a non-event.
Built for the shop floor, formatted for the finance office
HVI is a cloud + mobile CMMS — inspections, work orders, PM scheduling, parts and fuel — so the asset data finance needs is captured as a by-product of the work your team already does.
Per-unit asset ledger
Acquisition cost, in-service date, class, useful life and straight-line depreciation schedule on every unit — plus every work order and improvement costed against it. Export the full GASB-ready schedule any month of the year.
Photo-backed audit trail
Inspections, condition photos, disposal records and transfer logs are timestamped and attached to the unit. When an auditor asks about asset existence and condition, you show them — you don't describe it.
Work orders that feed the schedule
Every repair and capital improvement is costed to the unit automatically, so additions and betterments surface at year-end instead of hiding in a filing cabinet. That's the difference between a clean audit and a adjusting entry.
Accounting integrations
HVI connects with accounting and ERP systems, telematics and fuel cards, so acquisition data, meter readings and operating costs flow into one record. Finance and fleet finally read from the same page — literally.
Want to map this to your chart of accounts and capitalization policy? Bring your policy to a demo and we'll walk it through together.
GASB 34 fleet reporting, in one paragraph
If you remember nothing else, remember these four points.
The fleet is your biggest moveable asset class
At 40–70% of most municipalities' moveable capital assets, fleet data quality drives the quality of your entire government-wide statement. Get the fleet right and the rest is small.
The rules are stable — the data is the risk
Capitalize above your threshold (commonly $5,000), depreciate straight-line over class-based useful lives, record disposals promptly, and treat leases under GASB 87 and software subscriptions under GASB 96. None of that is hard if the underlying records exist.
Capture beats reconstruction, every time
Two to three weeks of annual audit prep collapses to minutes when acquisition, improvement and disposal data is logged as it happens. The cheapest audit is the one you were already ready for.
One system serves the shop and the finance office
HVI's CMMS runs your inspections, PM and work orders — and produces the fixed-asset schedule as a by-product. You don't buy fleet maintenance software for GASB 34; you buy it for uptime, and GASB 34 stops being a fire drill. Sign up free and see your first schedule before the next close.
"Every June I used to lose two weeks reconciling our fleet list against finance's register — chasing disposal paperwork, guessing at acquisition dates on trucks we bought before I got here. The number I watch now is simpler: how many minutes it takes me to answer an auditor's question about a specific unit. It used to be measured in days. With everything logged against the asset as we work — photos, costs, the lot — it's under five. My only gripe is we didn't do it before the 2021 audit, because that one still stings."
— Daniel Reyes, Fleet Services Manager, mid-size municipal public works fleet (140+ units)
GASB 34 fleet reporting: your questions answered
What is GASB 34 and does it apply to my municipal fleet?
What capitalization threshold should our fleet use?
How do we depreciate fleet vehicles under GASB 34?
How do GASB 87 and GASB 96 affect our fleet?
Can HVI produce the fixed-asset schedule our auditors ask for?
Make next June the easiest audit your fleet has ever had
Book a 30-minute demo and we'll load a sample of your fleet — trucks, plant, leased units — and show you the GASB-ready schedule it produces. Or jump straight in and build it yourself.
Free to start · Works on any phone · No card needed