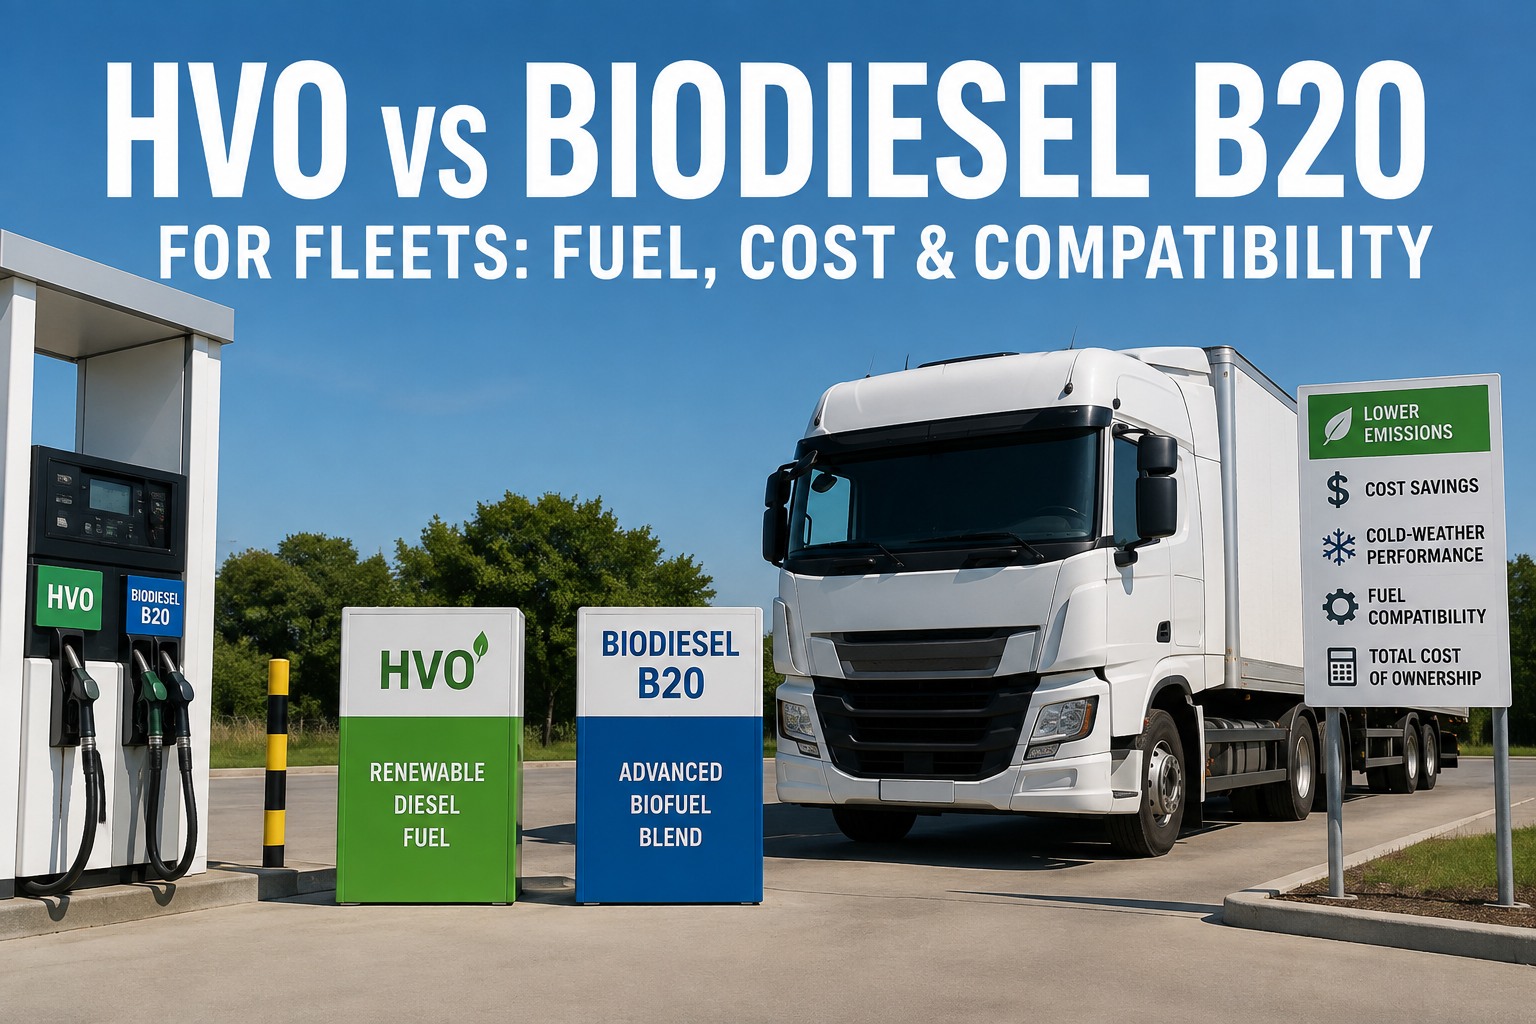
Renewable diesel R99 is the alternative-diesel fuel-switch that changes economics the moment your fleet operates in a region with a Low Carbon Fuel Standard. In California, the stack of LCFS credits, RIN values, and Section 45Z Clean Fuel Production Tax Credit routinely puts R99 net cost at or below fossil diesel — before the ~65% carbon intensity reduction. Outside LCFS states, the full renewable diesel premium applies. The TCO answer is regional, not universal — book a demo to analyse renewable diesel fleet TCO in HVI.
Renewable Diesel R99 — Net Effective Cost by Regional Policy Stack
Fleet operators asking "should we switch to R99?" get four different answers depending on which programme covers the region they operate in. Here's what actually stacks up.
R99 pump-price economics depend more on regional policy than on the fuel itself. The wholesale premium is real; the credit stack often erases it — but only where the stack exists.
The rest of this page walks the composition and compatibility of R99, the policy stack that decides the regional TCO answer, the ~5% volumetric fuel-consumption note that catches CFOs off guard, and the fleet-level pilot framework that turns "should we switch?" into a defensible per-asset number. Book a 30-minute demo to see per-asset fuel TCO in HVI.
What R99 actually is — the fuel behind the number
Renewable diesel R99 is a 99% renewable diesel + 1% ULSD blend, sold under names including R99, R99 renewable diesel, HVO, NExBTL renewable diesel, and green diesel. The 1% ULSD is present to satisfy US tax and regulatory tracking requirements; it does not change the fuel's operational characteristics meaningfully. R100 and HVO100 are 100% renewable equivalents sold in markets where the tracking requirement is different. All are the same base molecule: paraffinic hydrocarbon produced via hydrotreatment of renewable feedstocks (used cooking oil, tallow, soy, canola, other lipids) — chemically similar to fossil diesel and fully compatible with any diesel engine at any blend ratio.
| R99 property | Value / spec | Practical implication |
|---|---|---|
| Base standard | ASTM D975 No. 2-D (same as fossil diesel) | Drop-in replacement, no engine modification, no infrastructure change |
| EN standard | EN 15940 Class A (cetane ≥70) | Higher cetane than ULSD, cleaner combustion |
| Composition | 99% paraffinic hydrocarbon + 1% ULSD | Chemically similar to fossil diesel |
| Cetane number | 70-90 (vs ULSD ~50) | Improved combustion quality, cleaner burn |
| Density | 770-790 kg/m³ (vs ULSD 820-845) | ~5% lower volumetric energy content |
| Sulphur | <5 mg/kg (near zero) | Very low SOx emissions |
| Cold flow (winter) | CFPP -22°C to -32°C | Suitable for all Northern climates without additives |
| Storage life | ~10 years | Long-term storage, emergency reserves, seasonal fleets all workable |
| Life-cycle CO₂ reduction | 50-90% depending on feedstock & pathway | Substantial carbon-intensity improvement |
The single most important operational fact from that table for CFOs and fuel managers: R99 meets exactly the same ASTM D975 spec as fossil diesel, so every major diesel engine manufacturer (Cummins, Detroit, Volvo, PACCAR, Caterpillar, Scania) treats it as drop-in compatible with no warranty implications. The switch is a fuelling change, not a fleet change. Book a demo to see per-asset R99 fuel tracking with OEM compatibility flags in HVI.
The policy stack — why California R99 pricing looks nothing like Texas R99 pricing
Three overlapping policies drive the difference between R99 wholesale price and R99 net effective price to fleets. Understanding each is what separates a defensible fuel-switch business case from an aspirational one. California is the reference market because its Low Carbon Fuel Standard has been in place longest and issued more than $22 billion of credits since 2013.
LCFS credits
California, Oregon (CFP), Washington (CFS), British Columbia. R99 with low carbon intensity generates credits per gallon. LCFS prices traded $55-70/tCO₂e in 2026 — below the ~$200 ceiling but still meaningful. Value flows to producer/distributor, often to fleet via pump discount.
RFS D4 RINs
Federal Renewable Fuel Standard. Each gallon of R99 generates ~1.6-1.7 D4 RINs (proposal to reduce from 1.7 to 1.6 for 2026-27). Assumed ~$1/gal for 2026. Value tradeable, typically embedded in producer price and passed to fleet.
45Z Clean Fuel PTC
Federal Section 45Z tax credit (replaced $1/gal Blenders Tax Credit in 2025). Sliding scale by carbon intensity per 45ZCF-GREET. Producer-only, domestic feedstock preferred. Imported UCO ineligible. Value flows through wholesale price.
Carbon-priced contracts
Shippers with SmartWay, Scope 3, or carbon-scored logistics contracts are increasingly paying premium for R99-fuelled miles. Contract value ranges $0.02-0.15/mile depending on shipper commitment. Applies globally, not just in LCFS regions.
The stack works together, not independently. A single gallon of R99 delivered to a California fleet can carry an LCFS credit worth $0.20-0.35, a RIN value of ~$1.00, and 45Z PTC value on the production side that reduces the wholesale delivered price. Stack the three and the net effective cost frequently sits at or below fossil diesel. Outside LCFS regions the wholesale premium applies without offset, and net effective cost sits 15-70% above ULSD depending on market. The regional pricing gap is why any credible fleet-wide R99 decision needs to be built on the specific regions the fleet operates in, not on national average pricing. Fleets running across multiple regions (California + Nevada, Oregon + Idaho, UK + non-participating EU markets) often adopt a split strategy: R99 for miles inside credit-eligible regions, ULSD for miles outside — because the fuel-agnostic engines make split fuelling operationally trivial, and the cost math holds up cleanly under CFO scrutiny. Book a demo to see per-region R99 TCO modelling in HVI.
The volumetric fuel-consumption note CFOs miss
R99's lower density (770-790 kg/m³ vs ULSD's 820-845) means its volumetric energy content is roughly 5% lower than fossil diesel. In practice this translates to slightly higher fuel consumption by gallon — typically 2-4% more gallons burned per mile than the same truck on ULSD, depending on duty cycle. On per-mile carbon-intensity math this doesn't matter (R99's 50-90% CI reduction dominates), but on per-gallon cost math it modestly reduces the LCFS credit advantage. Any TCO calculation that compares R99 to fossil diesel on a $/gallon basis without adjusting for gallons-per-mile will overstate the R99 advantage.
The right way to run the TCO comparison: convert everything to cost per mile and carbon per mile, not $/gallon and CO₂/gallon. On per-mile carbon, R99 typically wins by 55-85% depending on feedstock even after accounting for the volumetric penalty. On per-mile cost, R99 wins comfortably in LCFS regions, sits near parity in partial-programme regions, and costs meaningfully more in non-programme regions. The regional split is the entire fleet-decision question. Start a free HVI trial to convert your fuel data to cost-per-mile and carbon-per-mile.
The 90-day R99 pilot — how to answer the fleet-wide question with data
A controlled pilot on 6-10 trucks over 90 days produces a defensible per-fleet R99 TCO number and beats every spreadsheet model built on regional averages. Four steps and the discipline to compare like-for-like.
Baseline
60 days pre-switch fuel and MPG data per pilot truck, matched to routes and drivers. Photograph fuel filters and injector condition at baseline for later comparison.
Switch to R99
Confirm OEM approval for each engine model, then switch pilot fuelling to R99. Capture per-gallon delivered cost including credit adjustments where applicable to your region.
90-day monitoring
Track MPG, DPF regen frequency, DEF consumption, any driver-reported change in performance, maintenance events. Same routes, drivers where possible. Compare like-for-like.
Per-fleet projection
Convert to $/mile and CO₂/mile for pilot, project across full fleet adjusting for route-region mix. Produce defensible payback and carbon-reduction number for CFO and sustainability review.
What most pilots discover: R99's operational impact is nearly invisible — MPG within measurement noise of baseline, no cold-weather issues, no maintenance disruption, cleaner DPF cycling. The economics come down entirely to regional credit stack. A CFO who models the pilot outcome against regional pricing on the fleet's actual routes produces a decision that survives scrutiny at board level. Book a demo to see pilot design and per-asset TCO tracking in HVI.
A West Coast fleet CFO on the LCFS math that made R99 the default
We run 165 tractors across California, Oregon, and Nevada. Corporate carbon target was 40% reduction by 2027. In Q1 2025 we ran a 90-day R99 pilot on 8 trucks — 4 California-based, 2 Oregon, 2 Nevada. Same routes, same drivers.
Fuel spend per California mile came out actually lower on R99 than ULSD once the LCFS credit and RIN passthrough hit the pump price. Oregon was near parity. Nevada was 34% higher per mile because none of the credits apply there. So we switched California and Oregon fleet-wide, kept Nevada on ULSD. Carbon-per-mile fleet-wide dropped 47% by end of 2025 — halfway to our 2027 target on a single fuel-switch decision. What we underestimated: the shipper premium. Two of our largest customers now specifically pay an uplift for R99-fuelled loads under their Scope 3 programme, which shifted the Nevada calculation too. We're piloting R99 in Nevada now on the strength of shipper contract value, not local credit value.
Frequently asked questions
What is renewable diesel R99?
Renewable diesel R99 is a 99% renewable diesel + 1% ultra-low-sulphur diesel blend, sold under names including R99, R99 renewable diesel, HVO, NExBTL renewable diesel, and green diesel. The 1% ULSD portion is present to satisfy US tax and regulatory tracking requirements; it does not change the fuel's operational characteristics meaningfully. R100 and HVO100 are 100% renewable equivalents sold in markets where the tracking requirement is different. All are the same base molecule: paraffinic hydrocarbon produced via hydrotreatment of renewable feedstocks (used cooking oil, tallow, soy, canola, other lipids). Meets ASTM D975 No. 2-D (US) and EN 15940 Class A (EU) — the same specifications as standard diesel — making it a drop-in replacement compatible with any modern diesel engine at any blend ratio. No engine modification, no fuel infrastructure change, no separate storage required. Cetane number 70-90 (vs fossil diesel ~50), density 770-790 kg/m³ (slightly lower than ULSD), sulphur near zero, cold flow to -22°C or -32°C in winter grades. Life-cycle CO₂ reduction of 50-90% depending on feedstock and production pathway. Approved by all major heavy-duty engine OEMs including Cummins, Detroit Diesel, Volvo, PACCAR, Caterpillar, and Scania.
How much does renewable diesel R99 cost compared to regular diesel?
Wholesale R99 typically costs 25-90% more than fossil diesel depending on region, feedstock, and supply availability. Net effective cost to fleets varies dramatically by policy region and can differ by 40 percentage points or more between California and non-LCFS states. In California, the stack of Low Carbon Fuel Standard credits (traded $55-70/tCO₂e in 2026), RFS D4 RINs (~$1/gallon assumed for 2026), and Section 45Z Clean Fuel Production Tax Credit routinely puts R99 net effective cost at or below fossil diesel. In Oregon (Clean Fuels Program) and Washington (Clean Fuel Standard), similar but slightly less generous programme stacks put R99 near parity with fossil diesel. In non-LCFS US states, only the RFS RIN and 45Z PTC apply, leaving R99 net effective cost 15-70% above ULSD. UK and EU pricing depends on national Renewable Transport Fuel Certificate schemes and RED III implementation. On per-mile carbon, R99 wins by 55-85% depending on feedstock. On per-mile cost, R99 wins in LCFS regions, sits near parity in partial-programme regions, and costs meaningfully more in non-programme regions. Regional pricing gap makes fleet-wide decisions region-specific.
Is R99 compatible with existing truck fleets?
Yes, universally on modern diesel engines. Because R99 meets the same ASTM D975 (US) and EN 15940 (EU) specifications as fossil diesel, every major heavy-duty engine manufacturer treats it as a drop-in replacement with no warranty implications and no engine modifications required. Cummins ISX/X15, Detroit DD13/DD15/DD16, Volvo D11/D13/D16, PACCAR MX-11/MX-13, Caterpillar C-series, and Scania all explicitly approve R99 and HVO including at 100% blend. Confirm against the specific engine spec sheet for each unit in your fleet before switching — older engines (pre-2007) may have specific requirements — but the pattern across modern equipment is universal approval. No changes required to fuelling infrastructure (storage tanks, dispensers, delivery equipment) because R99 behaves like fossil diesel in every operational respect. No fuel-filter change protocol required beyond standard PM (unlike biodiesel B20, which requires filter change vigilance in the first tank after switching). The switch is a fuelling change, not a fleet change — which is the primary reason renewable diesel has become the leading fleet-scale alternative diesel option in policy regions where the economics work.
Does R99 reduce fleet emissions?
Yes, substantially. Life-cycle carbon intensity reduction from switching fossil diesel to R99 typically falls in the 50-90% range depending on feedstock and production pathway. California LCFS certified carbon intensities show renewable diesel reduces carbon intensity by an average of about 65% compared to petroleum diesel. Tailpipe emissions are also lower than fossil diesel across most measured categories: nitrogen oxides (NOx), particulate matter (PM), carbon monoxide (CO), and hydrocarbons (HC) all measure lower on R99 due to the fuel's higher cetane number and cleaner combustion. Sulphur oxide (SOx) emissions are near-zero because R99's sulphur content is below 5 mg/kg (vs ULSD's 15 mg/kg limit). Diesel particulate filter regeneration frequency typically decreases 15-25% on R99 due to lower soot production, which extends DPF service intervals and reduces aftertreatment maintenance cost. Diesel Exhaust Fluid consumption remains similar. Fleets in Scope 3 or SmartWay reporting frameworks can claim the full life-cycle CO₂ reduction against their reported emissions, which increasingly matters for shipper contracts requiring carbon-scored logistics.
How does R99 perform in cold weather?
R99's paraffinic composition delivers Cold Filter Plugging Point (CFPP) values of -22°C to -32°C in winter grades — equivalent to or better than premium winter fossil diesel. Standard winter ULSD typically CFPPs around -20°C. No cold-flow additives, seasonal blend management, or storage tank monitoring for gelling are required to run R99 through Northern winters in Canada, Northern US, Northern Europe, or the UK. This is a substantial operational advantage over biodiesel B20 (CFPP -6 to -18°C depending on feedstock) which requires seasonal blend management or cold-flow additive dosing in cold climates. Storage stability is also excellent — R99 has approximately 10-year storage life vs biodiesel's 6-month life — making it suitable for long-term storage, emergency reserves, and seasonal-operation fleets. Water absorption is low and microbial growth risk in storage tanks is minimal (unlike biodiesel where oxygenated content promotes microbial issues). The combination of universal engine compatibility, drop-in specification match, excellent cold-flow performance, and long storage life is why R99 has emerged as the dominant fleet-scale alternative diesel in policy regions where the economics work.
Model your R99 switch on your regions, your routes, your data
HVI tracks fuel type, cost, and consumption per asset per region, converts every gallon to cost-per-mile and carbon-per-mile, holds LCFS-region and RIN pricing overlays, and produces the per-asset TCO you can compare pre- and post-transition. Run a controlled 90-day R99 pilot on 6-10 trucks, measure real fuel economy and maintenance impact, calculate real payback for your specific route-region mix — then scale on data. Live in under two weeks. No hardware. No credit card.
Trusted by fleets running R99, HVO & renewable fuels across USA, Canada, UK & EU · Ready on day one